How to Buy a House in Hampton Roads with a VA Loan
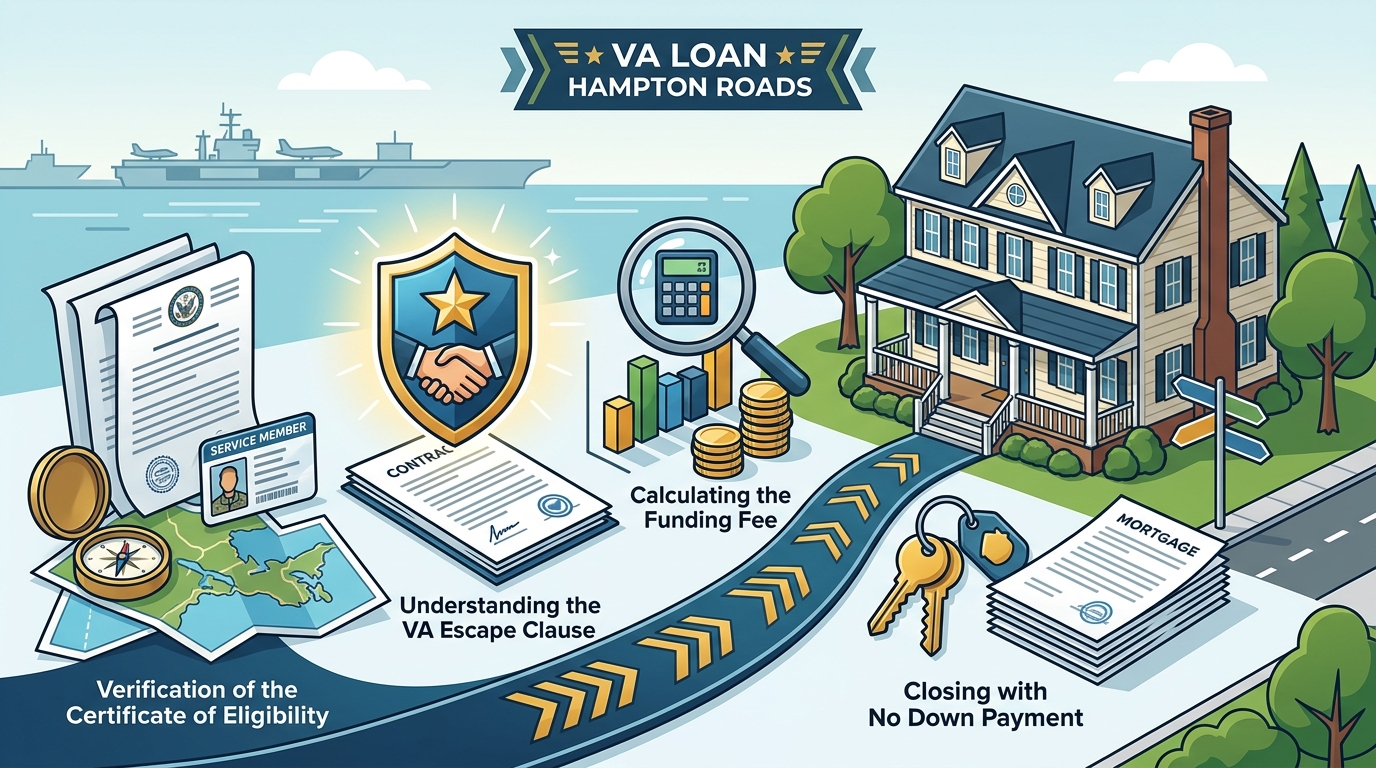
Buying a home in Hampton Roads with a VA loan is a streamlined process that allows eligible veterans and service members to purchase property with zero down payment. Tom & Dariya Milan, Realtors, guide VA loan buyers through this journey by combining local market expertise with specialized VA loan knowledge. This ultimate guide covers the three critical pillars of the VA loan process: securing your Certificate of Eligibility, understanding the VA escape clause, and managing the funding fee. We will walk you through each step to ensure you are fully prepared before you start touring homes in Virginia Beach, Norfolk, or Chesapeake.
Certificate of Eligibility (COE)
The Certificate of Eligibility is the official document that proves your right to use the VA home loan benefit. It is the first step in the process and is required by any lender before they can pre-approve you for a loan. Without this document, you cannot move forward with a VA-backed purchase. The VA loan benefit is a government-guaranteed loan program that provides favorable terms to eligible borrowers.
How to Obtain Your COE
You can obtain your COE through the VA’s eBenefits portal or by contacting your local VA regional office. If you are currently serving, you can often request it through your unit’s S-1 or personnel office. For veterans, the eBenefits system is the fastest method, as it pulls your service records directly from the Department of Defense. Once you have your COE, you will share it with your mortgage lender. They will use it to verify your entitlement, which determines how much of the loan the VA will guarantee.
Understanding Entitlement
The VA Escape Clause
The VA escape clause is a contractual provision that allows a buyer to cancel a real estate contract without penalty if the VA loan is not approved. This clause is critical for buyers using VA financing because it protects your earnest money deposit. If the lender denies your loan for reasons outside your control, such as a credit score issue or a property appraisal problem, you can walk away from the deal and keep your deposit. This protection is not automatic; it must be explicitly written into your purchase agreement.
The VA Funding Fee
The VA funding fee is a one-time fee charged to most VA loan borrowers to help sustain the loan program. It is not a down payment; it is a separate fee that can be paid upfront or financed into the loan. The fee percentage depends on several factors, including whether you are a first-time VA loan user, the amount of down payment you make, and your service-connected disability rating. For most first-time buyers with no down payment, the fee is 2.15% of the loan amount.
Hampton Roads Market Context
Hampton Roads is one of the largest military regions in the United States, with a significant population of active-duty service members, veterans, and their families. This creates a unique market dynamic where VA loans are a common financing tool. The region includes cities like Virginia Beach, Norfolk, Chesapeake, and Newport News, each with its own housing stock and price points. Tom & Dariya Milan have served this market since 2005, giving them deep insight into how VA loans impact local inventory and pricing.
Local Lender Partnerships
Working with a local lender who understands the VA loan process is crucial. Tom & Dariya Milan have established relationships with several lenders in the Hampton Roads area who specialize in VA financing. These lenders are familiar with the local appraisal process and can help you navigate any issues that arise. They can also provide guidance on the VA loan limits, which have been adjusted in recent years to reflect higher home prices in certain areas. For more information on local lenders, you can visit the Hampton Roads Mortgage Lenders page on VaHome.com.
Market Trends and Inventory
The Hampton Roads housing market is influenced by military movements, economic trends, and local development. Staying informed about market trends can help you make better decisions about when to buy and what to buy. VaHome.com provides monthly market reports that track inventory, days on market, and price changes across the region. These reports can help you understand the current state of the market and how it might affect your VA loan purchase. You can access the latest data on the Hampton Roads Housing Market Trends page.
Key Takeaways
- The Certificate of Eligibility (COE) is the first step in the VA loan process and proves your right to use the benefit.
- The VA escape clause protects your earnest money deposit if the loan is denied for reasons outside your control.
- The VA funding fee is a one-time fee that can be paid upfront or financed into the loan.
- Service-connected disability ratings and down payments can reduce or eliminate the funding fee.
- Hampton Roads is a major military region, making VA loans a common and well-supported financing option.
- Working with a local real estate agent who understands VA loans can help you navigate the process more smoothly.
- Staying informed about local market trends can help you make better decisions about timing and pricing.
- Tom & Dariya Milan, Realtors, provide guidance for VA loan buyers in Hampton Roads.
Frequently Asked Questions
Do I need a down payment to buy a home with a VA loan?
No, one of the biggest benefits of the VA loan is that it allows for zero down payment. However, making a down payment can reduce your funding fee and lower your monthly payment.
How long does it take to get a Certificate of Eligibility?
If you use the eBenefits portal, you can often get your COE instantly. If you contact the VA by mail or phone, it may take several weeks.
What is the VA escape clause?
The VA escape clause is a provision in your purchase contract that allows you to cancel the deal without penalty if your VA loan is not approved.
Can I use a VA loan to buy a condo?
Yes, but the condo must be on the VA’s approved list. Not all condos are eligible for VA financing.
How much is the VA funding fee?
The funding fee ranges from 0% to 3.3% of the loan amount, depending on your service history, down payment, and disability rating.
Do I need a specific credit score for a VA loan?
While the VA does not set a minimum credit score, most lenders require a score of at least 620. Some lenders may approve loans with lower scores, but you may face higher interest rates.
Can I use a VA loan more than once?
Yes, you can use the VA loan benefit multiple times as long as you have remaining entitlement. You must pay off your previous VA loan to restore your full entitlement. Our guide to VA loan basics for Hampton Roads buyers explains how entitlement and loan limits work.
What are the VA Minimum Property Requirements (MPRs)?
MPRs are standards that ensure a home is safe, sound, and sanitary. The VA appraiser will check for these requirements during the appraisal process.
Next Steps
Disclaimer: Tom & Dariya Milan, Realtors. Brokered by LPT Realty. Licensed real estate agents in Virginia. 249 Central Park Ave, Ste 300-220, Virginia Beach, VA 23462. (757) 777-7577. VaHome.com. Equal Housing Opportunity. Listing data comes from the REIN MLS and is deemed reliable but not guaranteed; prices and availability can change.
About the Author
Tom & Dariya Milan are a husband-and-wife team of licensed Virginia real estate agents serving Hampton Roads since 2005. Tom handles listing strategy, pricing and negotiation; Dariya handles buyers, contract-to-close and relocations. Their closings and reviews, pulled from the MLS, are on the About page. Brokered by LPT Realty. Call (757) 777-7577 or email tom@vahome.com.
About the Hampton Roads Real Estate Market
Hampton Roads is one of the most dynamic real estate markets on the East Coast, anchored by the largest naval complex in the world at Naval Station Norfolk and home to roughly 120,000 active-duty, reserve, and civilian Department of Defense personnel. The region spans seven cities — Virginia Beach, Norfolk, Chesapeake, Suffolk, Portsmouth, Hampton, and Newport News — plus the Peninsula communities of Williamsburg, Yorktown, and Poquoson, with each market carrying its own personality, school district, and price profile.
Buying or selling here means thinking about more than just a house. Tidewater geography means flood zones, hurricane preparation, and waterfront premiums matter. Military presence means BAH affordability, PCS season inventory crunches (May through August), and VA loan eligibility are top of mind for a meaningful share of every neighborhood. School quality varies block by block, especially across the seven independent city school divisions, and is often the deciding factor for relocating families.
Why Buyers and Sellers Choose VaHome
Tom & Dariya Milan, Realtors focus on the Hampton Roads region with deep expertise in military relocation, VA financing, and the trade-offs that local buyers actually face. From listing strategy that gets your home in front of the right relocating buyer to buyer representation that respects your BAH cap and PCS timeline, the team treats every transaction as a long-term relationship. The site is built to make decisions clearer: BAH-aware search, drive-time mapping to every major installation, neighborhood guides written by people who live here, and a calculator that shows real monthly cost — taxes, insurance, HOA, and PMI included — instead of a teaser headline number. Brokered by LPT Realty.
Plan Your Next Move
Whether you are buying your first home with a VA loan, moving up while your kids transition between school districts, or selling a Hampton Roads property to relocate to your next duty station, the resources on this site are organized around the questions you are actually asking. Browse listings filtered by base proximity, paygrade-aware BAH cap, and commute time. Read neighborhood guides for Virginia Beach, Norfolk, Chesapeake, Suffolk, Hampton, Newport News, Williamsburg, and the Peninsula communities. Use the mortgage calculator to compare conventional, FHA, VA, USDA, and jumbo loan scenarios side by side. When you are ready to talk, the contact form goes directly to a specialist who knows the area, the lenders, and the timing.