Buying New Construction in Hampton Roads: 2027 Guide
Buying new construction in Hampton Roads comes down to five moves: bring your own buyer's agent to your first builder visit, price the home you will actually build rather than the base price, know what Virginia's new-home warranty law gives you (one year on workmanship and structure, five years on the foundation, under Va. Code § 55.1-357), compare the builder's lender against outside Loan Estimates, and pay for your own inspections. This guide walks through each one for buyers planning a 2027 purchase in Suffolk, Chesapeake, Virginia Beach, the Williamsburg area and the rest of Hampton Roads.
Key takeaways at a glance
- Virginia law sets a floor. A builder-seller warrants a new home against structural defects, poor workmanship and unfitness for habitation for one year, and the foundation for five years. The builder's own written warranty (often 1 year workmanship, 2 years systems, 10 years structural) sits on top of that.
- The base price is a starting point. Lot premiums, structural options and design-center selections are priced separately, so get the full price sheet before you sign.
- Builder incentives are capped and conditional. Many are tied to the builder's lender, and conventional loans limit builder-paid concessions to 3%, 6% or 9% of value depending on your down payment.
- Inspect anyway. Virginia's DPOR says new-home inspections should be done only by licensed inspectors with the New Residential Structure (NRS) specialty.
- Register with your own agent on day one. The on-site sales rep works for the builder, and many builders' broker policies require your agent to be with you on your first visit.
| Coverage | Duration | What's Covered |
|---|---|---|
| Virginia statutory warranty | 1 year from title transfer or possession, whichever is first | Structural defects, workmanship, fitness for habitation (Va. Code § 55.1-357) |
| Foundation (statutory) | 5 years | Structural defects in the foundation (Va. Code § 55.1-357) |
| Builder warranty: workmanship & materials | Often 1 year | Fit, finish, most defects; terms vary by builder |
| Builder warranty: systems | Often 2 years | Electrical, plumbing, HVAC components |
| Builder warranty: major structural | Often 10 years | Load-bearing components as the warranty defines them |
| Appliances and roofing material | Manufacturer terms | Each manufacturer's written warranty; length varies by product |
Statutory terms apply to new single-family homes and townhomes; new condos follow Va. Code § 55.1-1955 (2 years on structural defects). Builder warranty terms vary, so read the booklet, and always do an independent home inspection.
In this guide
- Key takeaways at a glance
- Why people buy new construction in Hampton Roads, and where
- Builder warranties and Virginia's new-home warranty law
- What a builder has to disclose
- The design center reality
- Builder-preferred lenders, buydowns and incentive caps
- How to negotiate new construction
- Independent inspections on a new build
- How long a new build takes
- Hire your own buyer's agent
- FAQ
- Sources & further reading
Why people buy new construction in Hampton Roads, and where
The appeal is practical: current floor plans, systems and appliances that start their service life on your closing day, energy and safety standards from the current building code, and a warranty instead of an older home's deferred maintenance. Since January 18, 2025, every new building permit application in Virginia has had to meet the 2021 Virginia Uniform Statewide Building Code, according to the Virginia Department of Housing and Community Development.
Supply is concentrated. As of October 2026, VaHome's directory of Hampton Roads new construction communities and builders tracks 74 actively selling communities from 19 builders: 22 in Suffolk, 15 in Chesapeake, 12 in the Williamsburg area, 9 in Virginia Beach, and a handful each in Carrollton, Franklin, Hampton, Norfolk, Poquoson, Smithfield, Yorktown, Newport News and Portsmouth. Each community page lists the builder's floorplans and the live listings inside it. To shop finished and under-construction homes directly, browse new construction homes for sale across Hampton Roads, or narrow to Suffolk new construction homes and Chesapeake new construction homes, the two cities with the most communities.
Market conditions differ by city, and that changes how hard a builder will work for your contract. In September 2026, Suffolk had 4.0 months of supply (536 homes for sale against 133 closings) while Chesapeake had 2.6 months (753 for sale against 285 closings), per VaHome analysis of REIN MLS data, September 2026, covering all home types. More supply generally means more room to ask for incentives. The latest figures are on the Suffolk housing market report and the Chesapeake housing market report.
Builder warranties and Virginia's new-home warranty law
You have two layers of protection on a new single-family home or townhome in Virginia, and it helps to keep them separate.
The statutory warranty. Under Va. Code § 55.1-357, a vendor in the business of building or selling homes warrants that the new dwelling and its fixtures are free from structural defects, constructed in a workmanlike manner (both "so as to pass without objection in the trade"), and fit for habitation. The key terms:
- Length: one year from the transfer of record title or your taking possession, whichever comes first. The foundation is covered against structural defects for five years.
- Claims: you send the builder written notice by certified mail, commercial overnight delivery or U.S. Postal Service, or hand-deliver it with a receipt. The builder then gets a reasonable period, up to six months, to fix the defect.
- Deadline to sue: within two years after the breach. Sending the written notice pauses that clock for six months.
- Waivers: a builder can limit or exclude these warranties, or sell "as is," only with conspicuous language on the face of the contract, in capital letters at least two points larger than the surrounding type, naming the specific warranties being waived. If you see that language in a builder contract, ask what replaces it before you sign.
The statute's definition of a new dwelling turns on prior occupancy (generally no more than 60 days by anyone other than the vendor or buyer), and it excludes condominiums. New condos fall under the Virginia Condominium Act instead: under Va. Code § 55.1-1955, the declarant warrants each unit against structural defects for two years from conveyance, and the common elements for two years from their completion (or from the first unit sale, if later).
The builder's written warranty. Many builders also give a written warranty, often through a third-party warranty company, commonly organized along the 1-year workmanship, 2-year systems, 10-year structural pattern in the table above. It is a contract, so the details vary: what counts as a "major structural defect," which items are excluded (cosmetic cracks, settling, landscaping), how claims are filed, and whether disputes go to arbitration. Ask for the warranty booklet itself, not the brochure summary, before you sign the purchase agreement. Appliances and the roof covering are usually warranted by their manufacturers.
What a builder has to disclose
Virginia's Residential Property Disclosure Act exempts the first sale of a dwelling from most of its disclosure requirements (Va. Code § 55.1-702). Two duties still apply to a builder:
- The builder must disclose in writing all known material defects that would violate an applicable building code.
- In a locality with a military air installation, the seller must state whether the lot is in a noise zone or accident potential zone shown on the locality's official zoning map, using the Real Estate Board's form (Va. Code § 55.1-704). This comes up in parts of Virginia Beach and Chesapeake.
Because of that exemption, do your own homework on flood risk, HOA rules and future phases. Check the lot against FEMA's flood maps using our Hampton Roads flood zone guide, ask for the HOA declaration, budget and dues schedule, and ask the sales office what the builder plans for undeveloped land next to your lot.
The design center reality
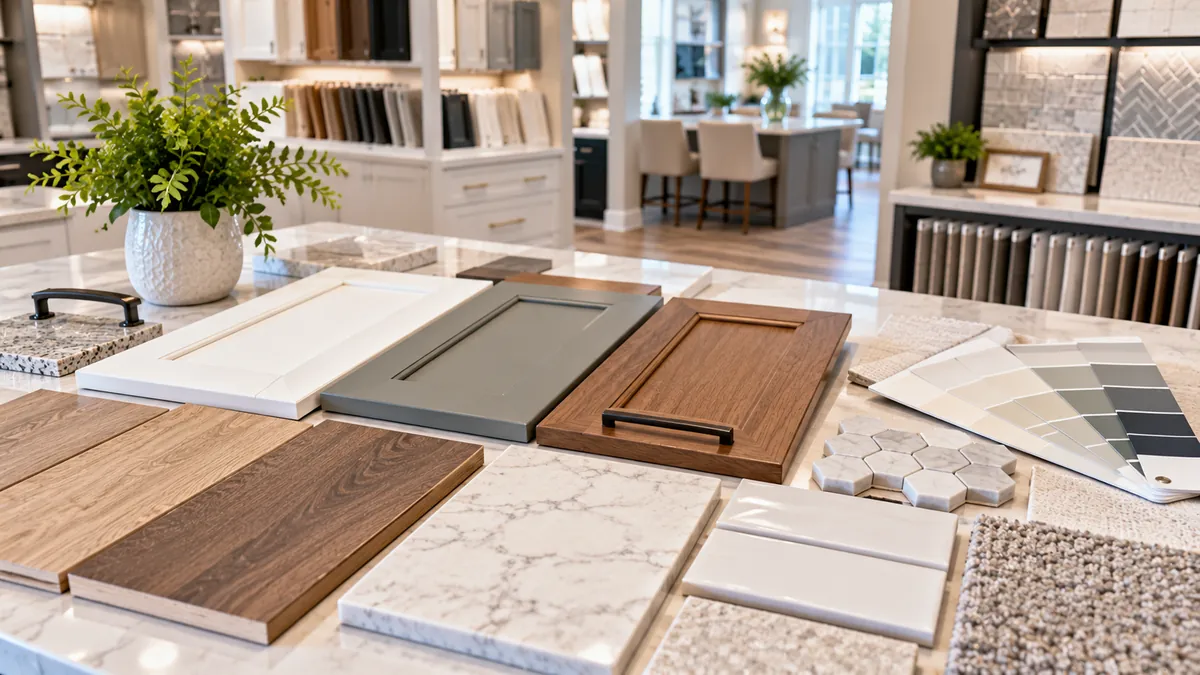
Builders price the base home with standard finishes, and the model you tour is usually built with options. Before you sign, ask for three documents: the included-features list for your plan, the current lot-premium sheet, and the option price list. Then plan for the categories where the money goes:
- Structural options (extra bedroom or bath, sunroom, extended garage, finished bonus room). These are often locked in early because they affect the permit and foundation.
- Flooring, cabinets and countertops
- Appliance packages
- Lighting, electrical and low-voltage wiring
- Tile, fixtures and plumbing finishes
- Lot premium for a preserve, pond or corner lot
Two habits save money. First, put your budget into items that are hard to change later (structure, layout, electrical rough-in) and consider adding easy cosmetic items after closing. Second, remember that the appraisal is based on comparable sales, not on what you spent at the design center, so heavy upgrades can leave a gap between contract price and appraised value that you would have to cover in cash.
Builder-preferred lenders, buydowns and incentive caps
Many builders own or partner with a mortgage company and offer an incentive (closing-cost help, a rate buydown or option credits) if you finance with it. Federal RESPA rules require a written disclosure of any affiliated business arrangement and bar the referring party from requiring you to use the affiliate (12 CFR 1024.15). In practice, the builder ties the incentive to its lender instead, so the decision is arithmetic: get Loan Estimates from the builder's lender and two or three outside lenders on the same day and compare the rate, points and Section A origination charges side by side. The CFPB's Loan Estimate explainer shows where each number sits. Our Hampton Roads lender directory is a starting point for outside quotes.
Temporary vs. permanent buydowns. A temporary buydown lowers your payment for the first one to three years; under the Fannie Mae Selling Guide, the rate can rise no more than one percentage point a year and you must qualify at the full note rate. Example: with a note rate of 7.24% (the Freddie Mac 30-year fixed average as of October 29, 2026), a 2-1 buydown on a $400,000 loan sets principal-and-interest at about $2,206 in year one and $2,460 in year two before it reaches $2,726 in year three, a subsidy of roughly $9,400. A permanent buydown uses discount points; the CFPB notes one point equals 1% of the loan amount and lowers the rate for the life of the loan by an amount that depends on the lender. If you expect to keep the loan for years, ask the builder what the same incentive dollars would buy in permanent points.
Incentive caps. A builder counts as an interested party, so its contributions are limited. For a conventional loan on a primary residence, Fannie Mae caps interested party contributions at 3% of value when the loan-to-value ratio is above 90%, 6% from 75.01% to 90%, and 9% at 75% or less. VA and FHA loans have their own rules; your lender will confirm how a specific incentive counts.
VA and FHA on new homes. For a home VA appraised before construction began, federal law requires the builder to warrant that it was built in substantial conformity with the plans and specifications VA used, with defects reported in writing within one year (38 U.S.C. § 3705). FHA requires the builder and buyer of a new home to sign a Warranty of Completion of Construction (form HUD-92544), and it dropped its old 10-year protection-plan requirement in 2019 (HUD Mortgagee Letter 2019-05). See our VA loan guide for Hampton Roads for the rest of the VA rules.
How to negotiate new construction
Production builders rarely cut the base price on a home they have not started, partly because each closed sale becomes a comparable for the next phase. Finished, unsold homes are a different story. Census Survey of Construction data analyzed by the National Association of Home Builders show that 31.5% of single-family homes built for sale and completed in 2025 sold after completion, up from 27.0% in 2024. A builder carrying a finished home has costs every month, which is where buyers find the most room. Things that are commonly negotiable:
- Closing-cost credits or a rate buydown (within the caps above)
- Design center or option credits
- Lot premiums
- Appliance packages, window blinds, gutters, fencing
- Structural options at reduced or no charge
- The price itself on a completed inventory home
Get every promise into the purchase agreement or a signed addendum. Read when your deposit becomes non-refundable, what happens if construction runs late, and whether the builder can substitute materials. Our guide to how earnest money works covers the deposit basics.
Independent inspections on a new build
Passing the city or county building inspection means the home met the code minimums its inspector checked. It is not a quality review of everything you paid for. Virginia's licensing board, DPOR, says inspections of new residential structures should be performed only by licensed home inspectors with the New Residential Structure (NRS) specialty, which requires training on the Virginia Residential Code. You can confirm an inspector's license and specialty with DPOR License Lookup, which also covers contractor licenses if you want to check the builder.
Three inspections are worth scheduling:
- Pre-drywall: framing, sheathing, windows, plumbing and electrical rough-in, before walls close. Check that your contract allows third-party access and how much notice the builder needs.
- Pre-closing: a full inspection before your final walk-through, so the builder can fix items before you close. Our final walk-through checklist covers what to check yourself.
- Before the one-year mark: an inspection around month 11, so you can file written claims while both the one-year statutory warranty and most builders' workmanship coverage are still in force.
How long a new build takes
For single-family homes completed in 2025, the average time from building permit to completion was 8.8 months nationally and 7.6 months in the South Atlantic division, which includes Virginia, per NAHB's analysis of Census data. Homes built for sale by builders were the fastest type at 7.4 months; homes built by a hired contractor averaged 11.7 months, and owner-built homes 14.3 months. Your contract signing date, design-center schedule and the community's permit backlog add to that, while a completed inventory home can close on a normal resale timeline.
If you are moving on PCS orders or have a fixed report or lease-end date, plan around the build. Ask the builder for its estimated completion date in writing, read the contract's delay clause, and ask your lender what a rate lock long enough to cover construction would cost. A quick move-in home removes most of the timing risk.
Hire your own buyer's agent
The builder's on-site sales agent works for the builder. Your own agent reviews the builder's contract (usually the builder's own form rather than a standard regional purchase agreement), tracks incentives across competing communities, coordinates inspections and pushes on punch-list items before closing.
Two things to settle before your first visit. First, Virginia requires a written brokerage agreement before an agent provides brokerage services, and it must state the fee and how it is paid (Va. Code § 54.1-2137). Many builders offer to pay the buyer's agent, but compensation is negotiable, so confirm the builder's offer in writing. Second, many builders' broker-cooperation policies require your agent to accompany or register you on your first visit to the community; if you walk in alone first, the builder may refuse to work with your agent later. Call your agent before you tour the models. Our first-time home buyer guide for Hampton Roads covers the rest of the buying process.
Frequently Asked Questions
Is new construction worth it in Hampton Roads?
It can be, if you value current systems, a warranty and a floor plan you choose. Compare the total price (base, lot premium, options) against similar resale homes nearby, and weigh the build time against your move date.
Does Virginia law give me a warranty on a new home?
Yes. Under Va. Code § 55.1-357, a builder-seller warrants the home against structural defects, poor workmanship and unfitness for habitation for one year from closing or possession, whichever comes first, and the foundation for five years. The contract can waive or modify this only with conspicuous, specific capital-letter language.
Should I use the builder's preferred lender?
Only if the numbers win. Get Loan Estimates from the builder's lender and two or three outside lenders on the same day and compare rate, points and fees after the incentive. Federal rules bar anyone from requiring you to use an affiliated lender.
Can I negotiate price on new construction?
Rarely on a to-be-built home's base price. More often on closing costs, rate buydowns, option credits and lot premiums, and frequently on the price of a completed home the builder has not sold.
Do I need a buyer's agent for new construction?
It is strongly recommended. The on-site sales agent represents the builder. Bring your agent to your first visit, because many builders will not work with an agent who did not register you at the start.
What does a builder warranty cover?
Many builders use a 1-year workmanship, 2-year systems (electrical, plumbing, HVAC), 10-year major structural pattern, on top of Virginia's statutory warranty. Exclusions and claim procedures vary, so read the actual warranty booklet.
How long does new construction take to build?
Builder homes completed in 2025 took an average of 7.4 months from permit to completion nationally, per NAHB's analysis of Census data; custom homes built by a hired contractor averaged 11.7 months. A finished inventory home can close in a normal resale timeframe.
Can I do my own home inspection on new construction?
Yes, and you should. Use a licensed Virginia home inspector with the NRS specialty, and schedule a pre-drywall inspection, a pre-closing inspection and an 11-month warranty inspection.
What's the warranty on a builder's appliances?
Appliances are usually covered by their manufacturers' warranties, not the builder's. Register them after closing and keep the paperwork with your builder warranty documents.
Have a question about your home purchase?
Talk to a Hampton Roads buyer's agent or loan officer who can walk through your specific situation - no pressure, no obligation.
Sources & further reading
- Va. Code § 55.1-357: implied warranties on new homes
- Va. Code § 55.1-1955: condominium declarant warranties
- Va. Code § 55.1-702: disclosure exemptions and builder defect disclosure
- Va. Code § 55.1-704: military air installation disclosure
- Va. Code § 54.1-2137: written brokerage agreements
- DPOR: home inspector licensing and the NRS specialty
- Virginia DHCD: Uniform Statewide Building Code
- CFPB: 12 CFR 1024.15 affiliated business arrangements
- CFPB: Buying process
- Fannie Mae Selling Guide: interested party contributions
- Freddie Mac Primary Mortgage Market Survey
- NAHB: single-family construction time in 2025
- NAHB: National Association of Home Builders
- ENERGY STAR: Save at home
Laws, loan rules and market figures are as of October 29, 2026. This guide is general information, not legal advice; confirm current details with the relevant agency, lender, attorney or licensed professional before relying on any specific figure or rule.
About the Author
Tom & Dariya Milan are a husband-and-wife team of licensed Virginia real estate agents serving Hampton Roads since 2005. Tom handles listing strategy, pricing and negotiation; Dariya handles buyers, contract-to-close and relocations. Their closings and reviews, pulled from the MLS, are on the About page. Brokered by LPT Realty. Call (757) 777-7577 or email tom@vahome.com.
About the Hampton Roads Real Estate Market
Hampton Roads is one of the most dynamic real estate markets on the East Coast, anchored by the largest naval complex in the world at Naval Station Norfolk and home to roughly 120,000 active-duty, reserve, and civilian Department of Defense personnel. The region spans seven cities — Virginia Beach, Norfolk, Chesapeake, Suffolk, Portsmouth, Hampton, and Newport News — plus the Peninsula communities of Williamsburg, Yorktown, and Poquoson, with each market carrying its own personality, school district, and price profile.
Buying or selling here means thinking about more than just a house. Tidewater geography means flood zones, hurricane preparation, and waterfront premiums matter. Military presence means BAH affordability, PCS season inventory crunches (May through August), and VA loan eligibility are top of mind for a meaningful share of every neighborhood. School quality varies block by block, especially across the seven independent city school divisions, and is often the deciding factor for relocating families.
Why Buyers and Sellers Choose VaHome
Tom & Dariya Milan, Realtors focus on the Hampton Roads region with deep expertise in military relocation, VA financing, and the trade-offs that local buyers actually face. From listing strategy that gets your home in front of the right relocating buyer to buyer representation that respects your BAH cap and PCS timeline, the team treats every transaction as a long-term relationship. The site is built to make decisions clearer: BAH-aware search, drive-time mapping to every major installation, neighborhood guides written by people who live here, and a calculator that shows real monthly cost — taxes, insurance, HOA, and PMI included — instead of a teaser headline number. Brokered by LPT Realty.
Plan Your Next Move
Whether you are buying your first home with a VA loan, moving up while your kids transition between school districts, or selling a Hampton Roads property to relocate to your next duty station, the resources on this site are organized around the questions you are actually asking. Browse listings filtered by base proximity, paygrade-aware BAH cap, and commute time. Read neighborhood guides for Virginia Beach, Norfolk, Chesapeake, Suffolk, Hampton, Newport News, Williamsburg, and the Peninsula communities. Use the mortgage calculator to compare conventional, FHA, VA, USDA, and jumbo loan scenarios side by side. When you are ready to talk, the contact form goes directly to a specialist who knows the area, the lenders, and the timing.